
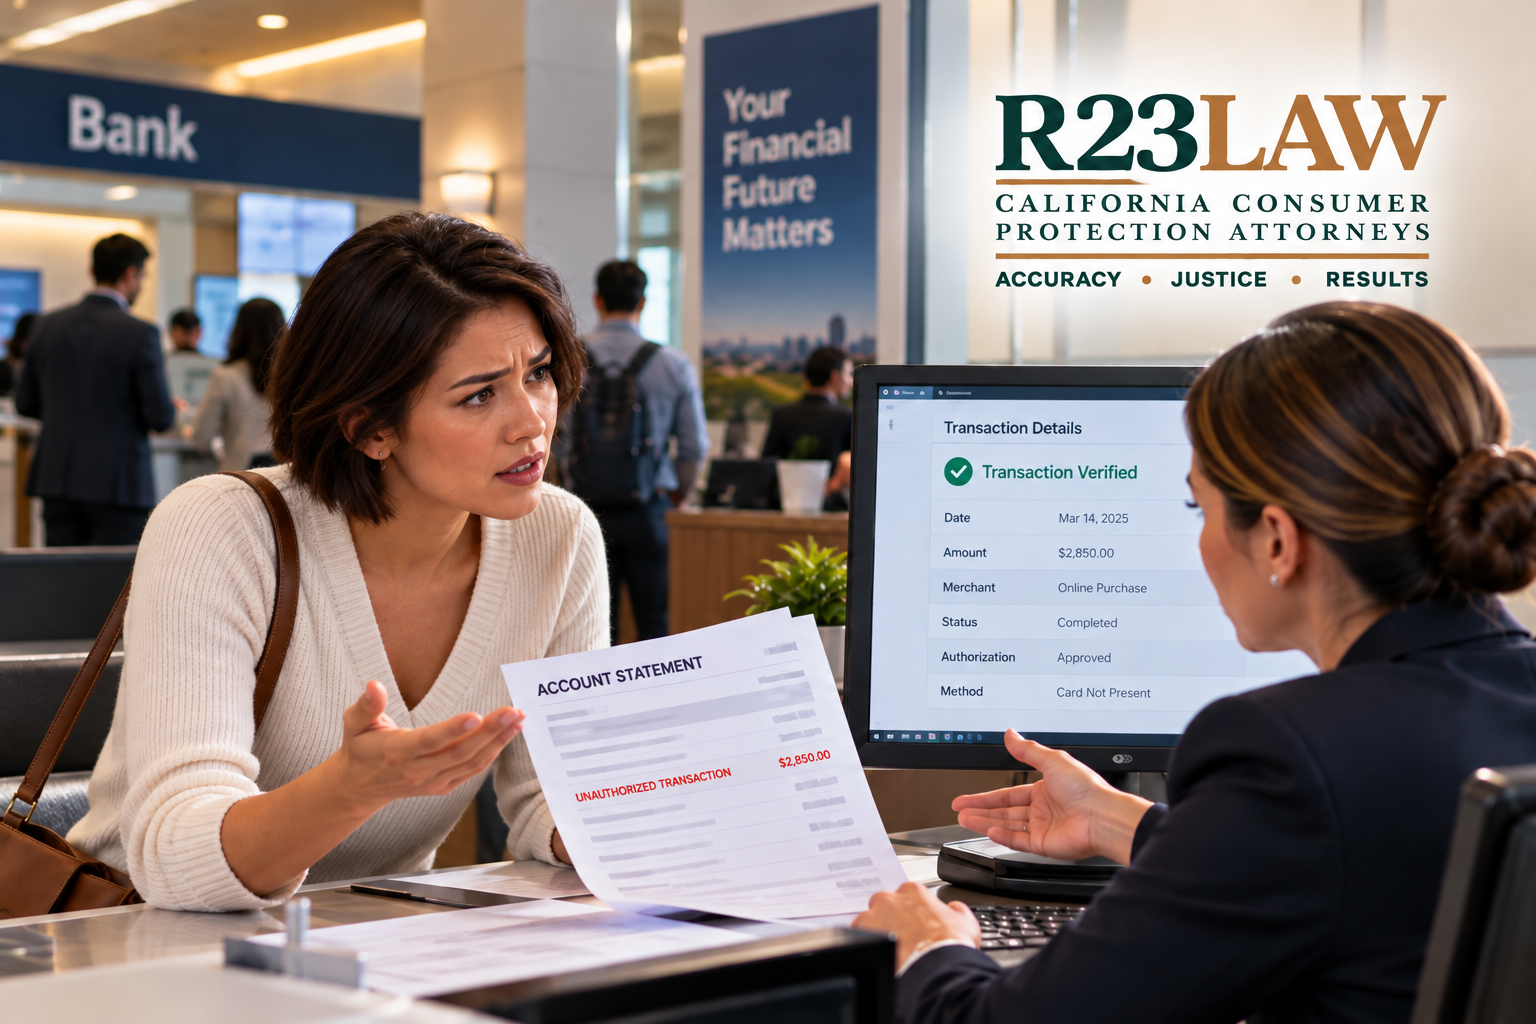
Discovering that someone has stolen your financial information is devastating
But for many California consumers, the frustration intensifies when banks and credit reporting agencies refuse to acknowledge the fraud.
You report an unauthorized transaction, only to be told the bank's records show it was legitimate. You dispute a fraudulent account, but the credit bureau responds that the information was verified.
Suddenly, the victim is expected to explain why the company's records are wrong.
Just because a transaction appears legitimate in a financial institution's system does not automatically mean the consumer authorized it.
At R23 Law, our experienced California Consumer Protection Attorneys advocate for victims of financial identity theft, unauthorized transactions, inaccurate credit reporting, and potentially unlawful dispute investigations.
WHEN RECORDS REPLACE REALITY — Why Financial Institutions Deny Fraud Claims
Banks, lenders, and credit reporting agencies rely heavily on electronic records to verify financial activity.
These systems may examine:
Account numbers and personal identifying information
Passwords, PINs, and login credentials
Recognized devices and IP addresses
Transaction histories
Credit applications and account records
When this information appears consistent, a financial institution may conclude that the activity was legitimate.
However, stolen credentials, compromised devices, and fraudulently obtained personal information can also generate seemingly legitimate records.
For example, an identity thief may open a credit account using a consumer's correct name, address, and Social Security number.
Although those details match the consumer, matching personal information does not establish that the consumer actually opened or authorized the account.
This distinction is especially important when financial institutions rely on automated verification systems without adequately examining evidence of fraud.
VERIFIED DOESN'T MEAN AUTHORIZED — The Problem With Inadequate Investigations
Two words frequently appear in financial fraud disputes — verified and authorized.
A credit bureau may declare an account verified after confirming information with the creditor that originally reported it.
Similarly, a bank may classify a disputed transaction as authorized because the correct PIN, password, or recognized device was used.
However, these conclusions may overlook the possibility that the information or account access was compromised.
Credit Reporting Disputes
Under the Fair Credit Reporting Act (FCRA), credit reporting agencies generally must conduct reasonable reinvestigations of qualifying disputes involving inaccurate or incomplete information.
Simply confirming existing records may not satisfy the law when the circumstances require a more thorough investigation.
Unauthorized Banking Transactions
When an unauthorized electronic fund transfer involves a covered consumer account, the Electronic Fund Transfer Act (EFTA) and Regulation E may provide important protections.
A transaction's use of valid credentials does not, by itself, establish that the consumer authorized the transfer.
Financial institutions must comply with applicable error-resolution requirements when investigating qualifying claims.
R23 Law's California Consumer Protection Attorneys evaluate potential violations involving improper credit reporting investigations and unauthorized financial transactions.
FRAUD BEHIND THE SCREEN — When Technical Evidence Tells Only Part Of The Story
Financial fraud can occur even when account activity appears normal.
Criminals may obtain access through:
Phishing Scams — Deceptive communications designed to steal login credentials.
Data Breaches — Unauthorized exposure of personal or financial information.
Account Hacking — Criminal access to online banking or financial platforms.
SIM-Swapping Fraud — Unauthorized control of a victim's phone number to intercept security codes.
Stolen Payment Information — Compromised credit cards, debit cards, or banking credentials.
These methods can allow criminals to conduct transactions that appear consistent with ordinary account activity.
A recognized device, familiar IP address, or correct password may be relevant evidence, but it does not necessarily establish authorization.
For victims, the consequences can include missing funds, fraudulent debts, damaged credit scores, and collection activity involving accounts they never opened.
CHALLENGING THE DENIAL — Protecting Your Rights After Financial Fraud
When a financial institution rejects a fraud claim or a credit bureau verifies an unauthorized account, consumers should preserve documentation and understand their legal rights.
Important steps may include:
Preserve Financial Records — Keep account statements, transaction details, dispute letters, and denial notices.
Document Unauthorized Activity — Identify fraudulent transactions, unfamiliar accounts, or inaccurate credit information.
Submit Formal Disputes — Notify the appropriate bank, creditor, or credit reporting agency through the applicable dispute process.
Report Identity Theft — Consider filing an identity theft report through the Federal Trade Commission at IdentityTheft.gov.
Review Your Credit Reports — Obtain reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com.
Prompt reporting is particularly important because certain financial protections involve specific deadlines.
California consumers may also receive protections under the California Consumer Credit Reporting Agencies Act (CCRAA) and other applicable consumer protection laws.
Depending on the circumstances, violations may support claims for financial losses, qualifying emotional distress damages, statutory remedies, or attorney's fees where authorized.
An unfavorable investigation outcome alone does not automatically establish a violation. Liability depends on the facts and the applicable legal requirements.
DEFENDING FRAUD VICTIMS — R23 Law's California Consumer Protection Attorneys
When banks and credit bureaus place greater confidence in their records than in evidence of unauthorized activity, consumers may face significant obstacles in resolving fraud.
At R23 Law, our California Consumer Protection Attorneys and California Identity Theft Victim Lawyers advocate for consumers affected by fraudulent accounts, unauthorized electronic transfers, inaccurate credit reporting, and potentially inadequate investigations.
Our attorneys evaluate claims involving the FCRA, EFTA, CCRAA, and other applicable consumer protection laws, pursuing available legal remedies when appropriate.
Our experienced legal team is committed to protecting consumers from unlawful financial practices and holding responsible institutions accountable.
Learn more about R23 Law and our consumer finance law practice.
SYSTEMS CAN BE WRONG — YOUR RIGHTS STILL MATTER
Financial institutions rely on sophisticated technology, but automated records are not infallible.
A successful login does not automatically prove consent. Matching personal information does not establish legitimate account ownership. And a credit bureau's verification does not necessarily mean its investigation satisfied federal law.
When banks or credit reporting agencies fail to properly address fraudulent activity, consumers may have legal remedies.
R23 Law's California Consumer Protection Attorneys are committed to protecting fraud victims throughout California from unlawful financial practices and inaccurate credit reporting.
Contact R23 Law Today
If a bank has denied your unauthorized transaction claim or a credit bureau continues reporting fraudulent accounts as legitimate, your consumer protection rights may have been violated.
Contact R23 Law's California Consumer Protection Attorneys to discuss your circumstances and explore available legal options under federal and California law.
Our legal team is dedicated to protecting consumers affected by financial identity theft, wrongful fraud denials, and unlawful credit reporting practices.
Toll-Free: 310-598-1588
SoCal: (310) 598-1588
Email: info@R23Law.com
Website: www.R23Law.com
Office: US Bank Tower, 633 W. 5th Street, 26th Floor, Los Angeles, CA
© 2025 R23 Law. All rights reserved. Trusted consumer credit lawyers in Los Angeles.
